Private health insurance may cover a mobility scooter when it is considered medically necessary durable medical equipment, usually for safe mobility inside the home. Approval often depends on your plan’s DME benefit, prior authorization rules, in-network supplier requirements, and documentation from your treating clinician. What you pay can range from very little after your deductible is met to the full cost if the scooter is not covered, not authorized, or purchased outside the plan’s rules.
This guide is for people reviewing employer, marketplace, union, retiree, or other non-Medicare private insurance. It does not replace your plan documents or medical advice, but it gives you a practical framework for asking the right questions before ordering a scooter.
How private insurance usually treats scooters: 1 DME benefit to check first
Most private insurance plans review mobility scooters under the durable medical equipment, or DME, benefit. DME generally means equipment that can withstand repeated use, serves a medical purpose, is appropriate for home use, and is ordered by a clinician. A mobility scooter may also be called a power-operated vehicle in some plan language.
The key word is may. Private plans vary widely. One plan may cover scooters after prior authorization, while another may cover manual wheelchairs and certain power wheelchairs but exclude scooters. Some plans cover only equipment needed for mobility-related activities of daily living inside the home, such as getting to the bathroom, kitchen, or bedroom. Trips to stores, parks, or social events may improve quality of life, but they are not always enough on their own to meet a medical necessity standard.
Start with your Summary of Benefits and Coverage, then look for the longer Evidence of Coverage or Certificate of Coverage. Search for 3 phrases: durable medical equipment, mobility assistive equipment, and exclusions. If the document says DME is covered at 80% after deductible, that still does not guarantee a scooter. It only explains the cost-sharing formula if the request meets the plan’s rules.
Who it is best for: 3 common approval patterns
Insurance coverage is most likely when the scooter addresses a documented safety or functional problem in the home, not just a convenience problem outside the home. A strong request usually fits one of 3 patterns.
- Limited walking endurance: The person can stand and transfer but cannot walk room-to-room safely or consistently, even with a cane or walker.
- Upper-body limits: The person cannot self-propel a manual wheelchair for needed daily activities because of pain, weakness, fatigue, coordination limits, or cardiopulmonary restrictions documented by a clinician.
- Safe scooter operation: The person can sit upright, transfer on and off, steer, control speed, understand safety instructions, and use the scooter in the home environment.
Coverage can be harder when the request is mainly for outdoor recreation, long shopping trips, travel, or caregiver convenience. It may also be denied if the home has tight turns, narrow doors, stairs at all entrances, or no place to charge the battery. A scooter that cannot be used where daily mobility needs occur may not meet the plan’s standard, even when the person clearly has mobility challenges.
A scooter is not the right tool for everyone. Some users need a different mobility aid because they require more seating support, cannot safely operate a tiller, or need help with transfers. A clinician or therapist can help match the equipment to the person’s physical abilities and home layout.
Medical necessity documentation: 6 items insurers often request
Private insurers usually want evidence, not a general note saying a scooter would be helpful. Requirements vary, but a complete packet often includes 6 items.
- A written order or prescription: This typically comes from a treating physician, nurse practitioner, physician assistant, or other eligible clinician under the plan.
- Recent clinical notes: The notes should describe the condition causing mobility limitation, how long it has been present, and how it affects daily function.
- Functional mobility details: Examples include how far the person can walk, whether falls have occurred, what assistive devices have been tried, and which daily activities are unsafe.
- Reason lesser equipment is not enough: The insurer may ask why a cane, walker, rollator, or manual wheelchair does not meet the need.
- Home use explanation: Many plans want to know the scooter is needed for essential movement inside the home, such as getting to meals, toileting, bathing, or sleeping areas.
- Supplier evaluation or therapist input: Some plans require measurements, photos, or a seating and mobility evaluation before approval.
Specific numbers help. For example, a note saying the person can walk about 20 feet with a walker before needing to sit is more useful than saying mobility is poor. A record of 2 falls in 3 months is more concrete than saying the person is at risk. The goal is not to exaggerate; it is to document real limitations clearly.
Prior approval process: 7 steps that may take 2 to 6 weeks
Many private plans require prior authorization before they will pay for a scooter. Buying first and requesting reimbursement later is risky. If authorization was required and not obtained, the plan may deny payment even when the scooter is medically necessary.
- Call member services: Ask whether mobility scooters are covered under your DME benefit and whether prior authorization is required.
- Confirm the billing code category: You do not need to master coding, but the insurer or supplier should identify the DME category used for the request.
- Choose an in-network DME supplier: Ask the plan for names, then call suppliers to confirm they accept your specific plan.
- Schedule the clinical visit: The clinician should document mobility limits and why the scooter is needed.
- Complete any equipment evaluation: The supplier, and sometimes a physical or occupational therapist, checks fit, safe operation, and home access.
- Submit the packet: The supplier often submits the authorization request, but you should ask for the submission date and reference number.
- Wait for a decision: Many routine DME decisions take about 2 to 6 weeks, though urgent or incomplete cases can be faster or slower depending on the plan.
If the insurer asks for more information, respond quickly and keep copies. A missing office note or unsigned order can delay approval more than the medical review itself.
What you may pay: deductibles, coinsurance, and 10% to 40% cost shares
Your cost depends on your plan design and timing. Common private insurance cost categories include deductible, coinsurance, copay, out-of-pocket maximum, and noncovered charges. One plan might pay a percentage of the allowed amount after the deductible is met, while another may use a fixed copay for DME.
Coinsurance for DME often falls into a percentage structure, such as 10%, 20%, 30%, or 40%, but your exact share is plan-specific. If you have not met your deductible, you may pay the plan’s allowed amount until the deductible is satisfied. If you have met your out-of-pocket maximum for the year, covered in-network costs may be paid at 100%, but only if the scooter is approved and all plan rules are followed.
Be careful with the phrase covered. It does not always mean free. It also does not mean any scooter, from any seller, at any price. Private insurance usually bases payment on an allowed amount, and the supplier may need to accept that amount under contract. Accessories, delivery, batteries, ramps, lifts, baskets, upgraded seating, or travel features may have separate rules or may not be covered.
| Cost term | What it means | Why it matters |
|---|---|---|
| Deductible | Amount you pay before the plan starts paying many benefits | A scooter approved early in the year may cost more out of pocket |
| Coinsurance | Your percentage of the allowed amount | A 20% share is different from 20% of a retail sticker price |
| Copay | Fixed dollar amount for a covered service or item | Some plans use copays instead of coinsurance for DME |
| Allowed amount | Plan-approved payment level for a covered item | Out-of-network sellers may bill more than this amount |
| Out-of-pocket maximum | Annual cap on covered in-network cost sharing | Noncovered items and balance bills may not count |
Network rules: 4 questions before choosing a supplier
Network rules are one of the biggest differences between private insurance and cash shopping. The supplier that is easiest to find online may not be contracted with your plan. If you buy from a nonparticipating seller, the plan may deny the claim or pay less.
Ask these 4 questions before you agree to an order:
- Is this supplier in network for my exact plan? The same insurance company may have multiple networks.
- Will the supplier obtain prior authorization? If yes, ask when and how you will be notified.
- Will I receive a written estimate? It should separate covered equipment, noncovered upgrades, delivery, and service fees when possible.
- Who handles repairs and warranty service? Insurance may treat repairs differently from the original purchase, especially after a rental period.
Some plans rent DME before purchase, while others purchase approved equipment outright. Rental periods can be 3 months, 10 months, 13 months, or another plan-specific schedule. During a rental, maintenance responsibilities may differ from those after ownership transfers. Ask whether batteries, chargers, tires, and normal wear are included, because those details affect real-world cost.
How to choose and measure: 32-inch doors, turning space, and safe fit
Insurance approval should match the person and the home. A scooter that is too large for the hallway or too heavy for the threshold will not solve the mobility problem the plan is reviewing. Before the supplier evaluation, take basic measurements.
- Doorway width: Many interior doors are about 28 to 32 inches wide, but older homes may be narrower. Measure the clear opening with the door fully open.
- Hallway width: Note tight corners, furniture, rugs, and floor transitions over 1/2 inch.
- Turning areas: Measure bathrooms, bedrooms, and kitchen paths where the scooter must turn or back up.
- User fit: Record approximate height, weight, seat width needs, leg position, and ability to reach the tiller controls.
- Charging location: Identify a dry indoor outlet with enough space around the scooter.
- Transport needs: If the scooter must go in a vehicle, ask whether transport features are covered or considered noncovered convenience features.
Do not assume a smaller scooter is always safer. Compact scooters may turn more easily, but they may have lower weight capacities, smaller wheels, and less support. Larger scooters may feel steadier outdoors but may be difficult inside a small home. The right choice is the one that meets the documented medical need in the actual environment.
Comparing scooter types: 3-wheel, 4-wheel, portable, and heavy-duty options
Private insurance is usually less interested in style and more interested in medical need, safe use, and the least costly appropriate option under the plan. Still, understanding the common scooter types helps you have a more informed discussion with the supplier.
| Generic scooter type | Typical strengths | Common tradeoffs | Insurance note |
|---|---|---|---|
| 3-wheel scooter | Tighter turning and easier maneuvering in small spaces | May feel less stable on uneven outdoor surfaces | May be considered when indoor turning space is limited |
| 4-wheel scooter | More stable feel for many users, especially on straight paths | Larger turning radius than many 3-wheel designs | Home layout still matters if indoor use is required |
| Portable or travel scooter | Breaks down into pieces for vehicle transport | Often less seating support and smaller batteries | Transport convenience may not be enough for coverage |
| Heavy-duty scooter | Higher weight capacity and larger frame | Heavier, wider, and harder to maneuver indoors | Needs documentation for size, capacity, and safe home access |
Features can matter as much as the base type. A comfortable seat, tiller adjustability, anti-tip design, lighting, speed controls, and appropriate tires can affect safe use. Coverage for upgraded features depends on whether they are medically necessary or simply preferred.
| Feature | Why it may matter | Documentation that can help |
|---|---|---|
| Seat width and support | Affects posture, pressure, and safe transfers | User measurements and clinician or therapist notes |
| Turning radius | Determines whether the scooter can work indoors | Hallway, doorway, and room measurements |
| Weight capacity | Must safely support the user and any needed positioning | Current weight and supplier fit assessment |
| Battery range | Supports daily use between charges | Daily home mobility routine and charging access |
| Disassembly | Helps with transport outside the home | Plan may view this as convenience unless tied to covered need |
If the request is denied: 180 days is a common appeal window
A denial is not always the end of the road. Many private plans allow an internal appeal, and 180 days from the denial notice is a common timeframe, though your plan may use a different deadline. Read the denial letter carefully. It should explain the reason and how to appeal.
Common denial reasons include lack of medical necessity, missing prior authorization, out-of-network supplier, insufficient documentation, plan exclusion, or a finding that a lower-level device would meet the need. Your appeal should respond directly to the stated reason. If the letter says the scooter is not needed inside the home, provide clinical notes and home examples that address indoor mobility. If it says a walker should be sufficient, ask the clinician to document why it is not safe or effective.
Keep the appeal organized. Include the denial letter, member information, authorization number, clinician letter, relevant office notes, therapy evaluation if available, home measurements, and a short personal statement about essential daily activities. Avoid emotional exaggeration. A clear, specific appeal is easier for a reviewer to approve than a long packet without a focused argument.
Call checklist: 12 questions to ask your private insurer
Before ordering, call the number on your insurance card and write down the date, representative name, and call reference number. Use these 12 questions to reduce surprises.
- Are mobility scooters covered under my DME benefit?
- Is there any plan exclusion for scooters or power-operated vehicles?
- Is prior authorization required before delivery?
- What documentation is required from my clinician?
- Do I need an evaluation by a physical or occupational therapist?
- Must I use an in-network DME supplier?
- Can you give me 2 or 3 in-network supplier options?
- Is the scooter rented first, purchased, or handled case by case?
- What is my deductible remaining today?
- What coinsurance or copay applies to approved DME?
- Do repairs, batteries, and replacement parts have separate coverage rules?
- How do I appeal if the request is denied?
After the call, compare what you were told with the written plan documents. Phone guidance is useful, but the plan document controls if there is a conflict.
FAQ: 5 private insurance scooter coverage questions
Does private insurance cover scooters for outdoor use?
Sometimes, but outdoor-only use is less likely to qualify on its own. Many plans focus on whether the scooter is medically necessary for essential mobility inside the home. Outdoor safety and community access may support the request, but they may not meet the coverage standard alone.
Do I need a prescription for a mobility scooter?
Usually yes if you want insurance to consider payment. Most plans require a written order and clinical notes from a treating clinician. Some also require a supplier assessment or therapy evaluation.
Can I buy a scooter online and submit the receipt?
That is risky. If your plan requires prior authorization or an in-network supplier, reimbursement may be denied. Call your insurer before purchase and ask whether reimbursement is allowed.
Will insurance pay for a folding or travel scooter?
It depends on the plan and the documented need. If folding is mainly for convenience or car travel, it may not be covered. If a compact design is needed for safe use in the home, the documentation should explain why.
What if my doctor agrees but insurance denies it?
You can usually appeal. Ask for the denial reason in writing, then have your clinician address that reason with specific functional details, measurements, and notes about why lesser equipment is not adequate.
Frequently asked questions
Does private insurance cover scooters for outdoor use? +
Sometimes, but outdoor-only use is less likely to qualify by itself. Many plans focus on whether the scooter is medically necessary for essential mobility inside the home.
Do I need a prescription for a mobility scooter? +
Usually yes if you want insurance to consider payment. Most plans require a written order and clinical notes from a treating clinician, and some require a supplier or therapy evaluation.
Can I buy a scooter online and submit the receipt? +
That is risky. If your plan requires prior authorization or an in-network DME supplier, reimbursement may be denied even if you have a medical need.
Will insurance pay for a folding or travel scooter? +
It depends on the plan and the documented need. Folding or transport features may be denied if they are viewed as convenience rather than medically necessary.
What if my doctor agrees but insurance denies it? +
You can usually appeal. Read the denial reason, then submit focused documentation that addresses medical necessity, home use, and why lesser equipment is not adequate.
Related guides
Mobility Scooter Prior Authorization Checklist: What to Ask Your Doctor, Plan, and Supplier
12 min read
Does Medicare or Insurance Cover Mobility Scooters? A US Buyer’s Guide
12 min read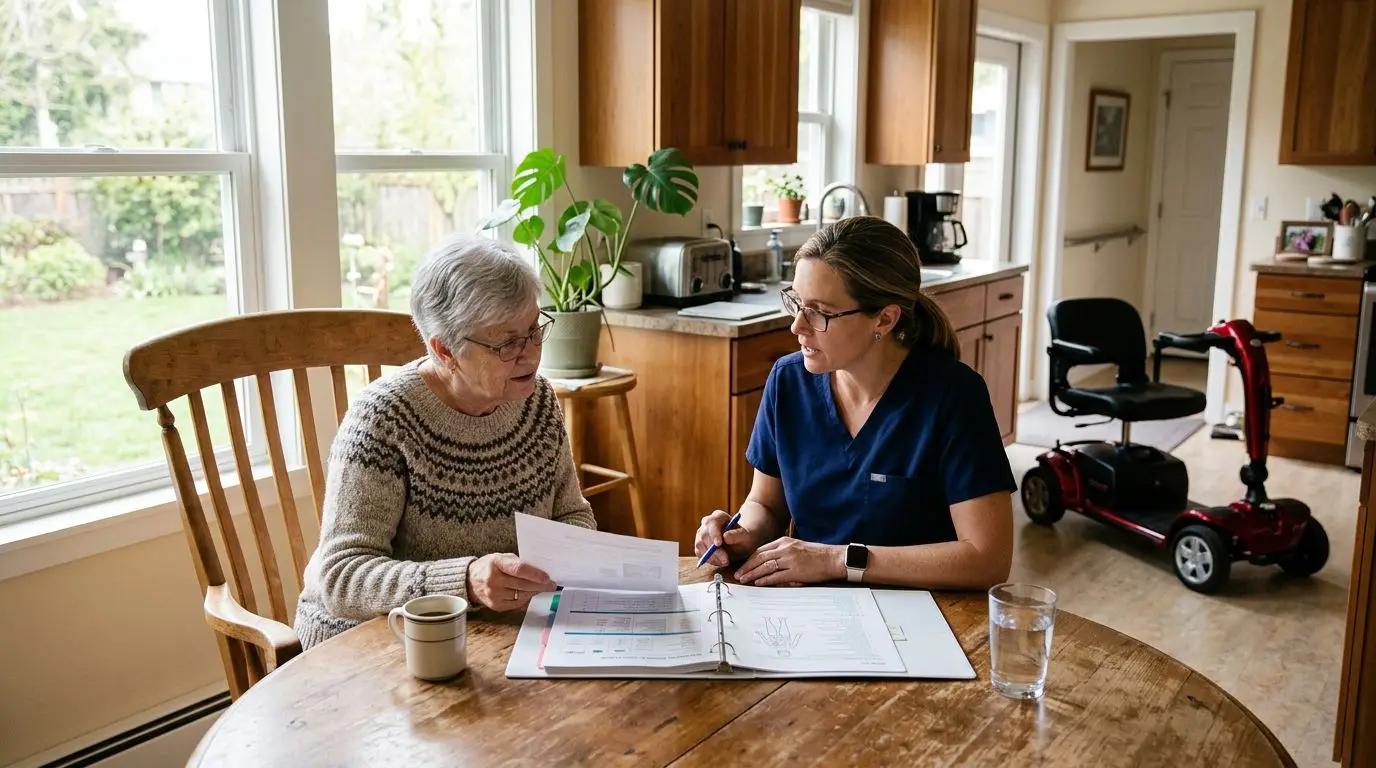
Mobility Scooter Prescription Requirements: What Doctors Must Document for Insurance Approval
14 min read